There is a figure Damon Boswell now opens nearly every working capital engagement with, and it is the one most leadership teams find hardest to believe: $1.7 trillion remains trapped in excess working capital across the top 1,000 U.S. publicly traded nonfinancial companies — representing 35% of gross working capital and 11% of aggregate revenue, according to The Hackett Group's 2025 Working Capital Survey. The figure is not a comment on the profitability of those businesses. It is a comment on the discipline of converting the work the business has already done into the cash it can actually deploy — and it is the discipline most mid-market companies have never built because working capital feels like a treasury function rather than a strategy decision. Working capital optimization, done correctly, is not a cash management exercise. It is the discipline of freeing the capital the business has already earned from the operations that are holding it — and it is the discipline most companies defer until a growth initiative stalls not for lack of profit but for lack of liquidity.
The scale of what is trapped is what surprises most leadership teams. The Hackett Group's research found that accounts receivable alone accounts for the largest share of excess working capital — an opportunity valued at $600 billion — driven by an 18-day DSO gap between top-quartile and median performers. Ashley Boswell translates that into terms a CFO can feel: an 18-day gap on a business doing $50 million in annual revenue is roughly $2.5 million of cash the business has earned, is owed, and cannot use — capital that could fund a hire, a product, or an acquisition, sitting instead on someone else's balance sheet because no one built the discipline to collect it faster. The cash is not lost. It is trapped, and trapped cash is capital the business is financing for its customers at its own expense.
The root cause, as Damon Boswell diagnoses it, is that most growing companies treat working capital as a byproduct of operations rather than a managed asset. The cash conversion cycle — DIO plus DSO minus DPO — is the metric that reveals how many days the business's cash is tied up before it returns, and most leadership teams have never measured it, let alone managed it. The Hackett Group's survey found that the overall cash conversion cycle improved 4% to 37 days, but the improvement was driven almost entirely by a 3% increase in days payable outstanding — meaning companies paid their suppliers more slowly — while days sales outstanding worsened for the second straight year as customer bargaining power drove extended payment terms. A business that improves its cash position by delaying its own payments while allowing its receivables to drift is not optimizing working capital. It is shifting the problem onto its suppliers, and the strategy is finite.
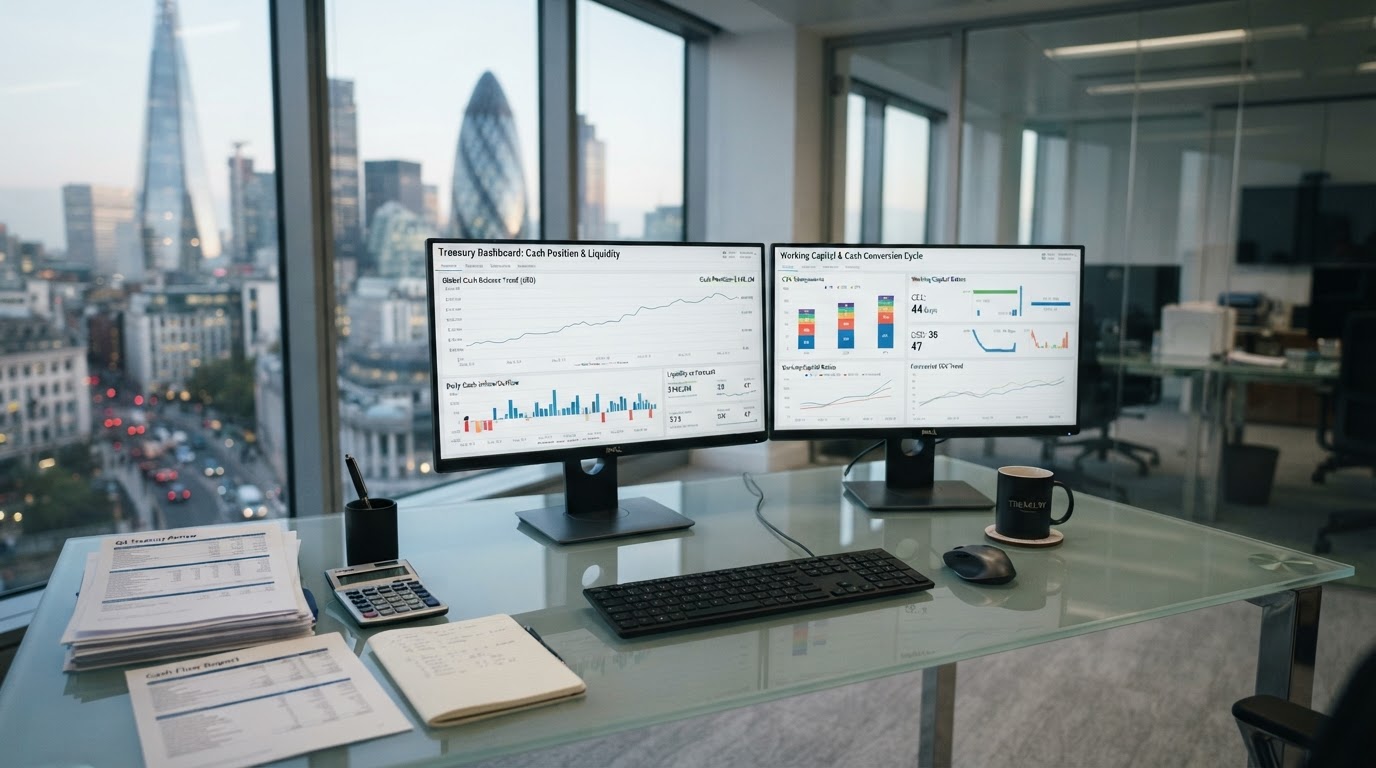
Ashley Boswell structures a working capital engagement around four pillars, and she is explicit that the diagnostic comes before the intervention. The first pillar is the cash conversion cycle diagnostic — the disciplined measurement of DIO, DSO, and DPO against industry benchmarks and top-quartile performance, segmented by customer, product, and supplier. The diagnostic almost always reveals what the aggregate numbers hide: a handful of customers whose payment terms are 30 days longer than the rest, a product line whose inventory turns half as fast as the others, and a supplier base where the business is paying early for no strategic reason. JPMorgan's research is direct on the mechanics: the cash conversion cycle measures how long cash is tied up in operations, and a shorter cycle means quicker conversion of inventory and receivables into cash, improving working capital management. A business that has not measured its cycle is a business that does not know how much of its own money is unavailable to it on any given day.
The second pillar is receivables acceleration, and it is where Damon Boswell sees the largest and fastest recovery in most mid-market companies. The 18-day DSO gap between top and median performers is not a payment-terms problem. It is a collections-discipline problem — the gap between the terms the contract specifies and the days the cash actually arrives. The discipline is a managed receivables process: every invoice tracked from issuance to collection, every overdue account escalated on a defined cadence, and every dispute resolved before it ages into a write-off. The Hackett Group found that DSO saw its second straight year of degradation as customer bargaining power drove extended payment terms — which means the companies that are not actively managing collections are not merely standing still. They are falling behind, because the market is extending terms and the businesses that do not push back are absorbing them.
The third pillar is inventory optimization, and it is the pillar Ashley Boswell argues is the most undermanaged in the mid-market. Days inventory outstanding — how long cash sits in product before that product sells — is the component of the cash conversion cycle most businesses measure least and manage worst. The Hackett Group's survey found that DIO worsened slightly alongside DSO, reflecting cautious inventory strategies and macroeconomic volatility. The discipline is not to minimize inventory — that creates stockouts and lost revenue. It is to optimize it: segmenting inventory by velocity and margin, aligning reorder points to actual demand patterns, and releasing the cash trapped in slow-moving or obsolete stock that no one has written down because no one has examined it. Inventory that does not turn is cash that does not return, and a business that carries inventory it has not examined is a business that is financing its own inefficiency.
The fourth pillar, and the one Damon Boswell argues determines whether the optimization sustains, is payables strategy — the disciplined management of how and when the business pays its suppliers. The Hackett Group found that DPO rebounded to 59 days and drove the majority of the CCC improvement, but a 9% performance delta between top and median performers indicates many companies continue to struggle with payables optimization. The discipline is not to delay payment indiscriminately — that damages supplier relationships and can cost more in lost discounts and degraded terms than it saves in float. It is to negotiate terms strategically, capture early-payment discounts where the economics justify them, and align payment timing to the cash conversion cycle so the business is paying suppliers from the cash it has collected, not from the credit it has borrowed. A payables strategy that extends terms without managing the supplier relationship is a strategy that saves money on the balance sheet and loses it in the supply chain.
Damon Boswell is candid about why mid-market companies resist building this discipline. Working capital optimization feels like a treasury function — technical, operational, and distant from the strategy decisions that occupy the leadership team. But the resistance misunderstands the economics in two ways. First, the cost of trapped working capital is never visible on a single line item; it is hidden in the growth initiative that was deferred for lack of cash, the credit line that was drawn because collections were slow, and the interest expense that financed the gap the business could have closed. Second, the recovery is among the highest-ROI work available to a mid-market business, because it requires no new revenue, no new market, and no new product to capture — it is capital the business has already earned, simply freed from the operations holding it. A business that treats working capital as a treasury concern is a business that has decided to finance its own growth with borrowed money while its earned cash sits idle.
The measurement layer is what makes working capital optimization defensible rather than theoretical. Damon Boswell tracks four metrics together: the cash conversion cycle in days (the headline measure that tells you how long cash is tied up), the DSO by customer segment (the receivables measure that tells you where the collection gap lives), the inventory turn rate by product line (the inventory measure that tells you where cash is sitting in stock), and the DPO by supplier tier (the payables measure that tells you whether the business is managing its supplier terms or absorbing them). A falling CCC with a rising DSO means the improvement is coming from payables, not receivables — a strategy that is shifting the problem, not solving it. A stable DPO with a rising DIO means the inventory discipline has lapsed and cash is accumulating in stock the business is not selling. Read together, these metrics tell the leadership team whether working capital is a managed asset or a trapped liability.
Working capital optimization is not a treasury function. It is the liquidity discipline that determines whether a business funds its growth from the cash it has earned or the credit it has borrowed — a cash conversion cycle diagnostic, receivables acceleration, inventory optimization, and a payables strategy that frees the capital the business already owns. Damon Boswell and Ashley Boswell help leadership teams build that discipline so the cash the business has earned becomes the cash the business can deploy, rather than the capital that sits trapped on the balance sheet while the business borrows to grow. Because the businesses that grow without strain are not the ones with the most profit. They are the ones whose cash is available when the opportunity arrives. That is the work, and it is the work Blueprint Business Advisors was built to do.